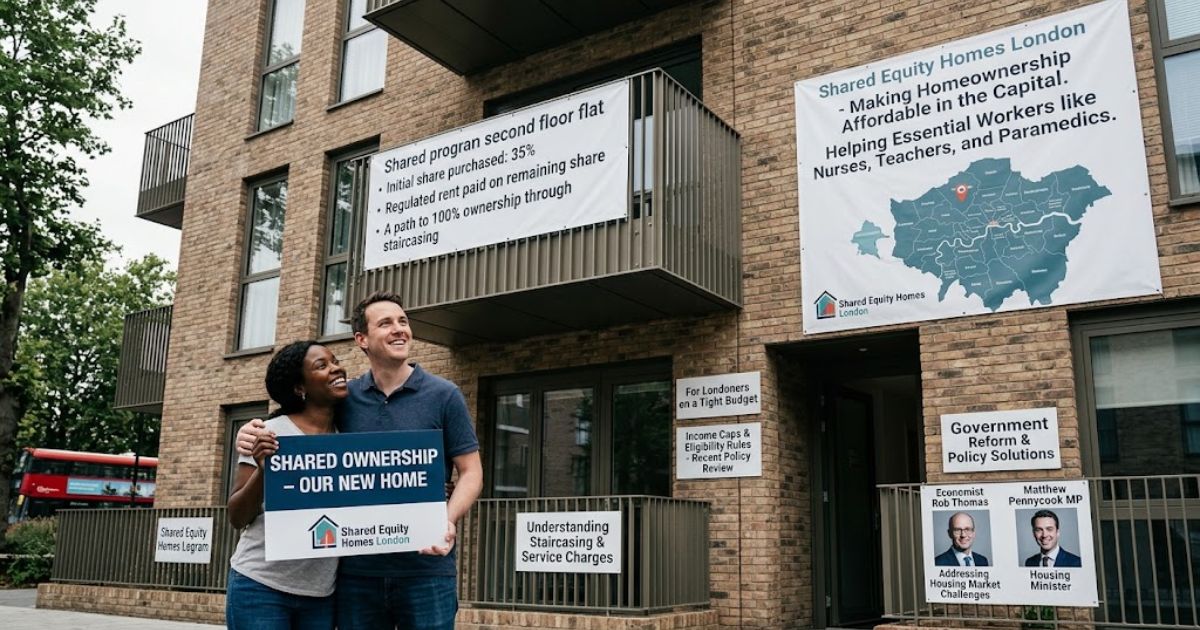
Londoners who search for a new home on a tight budget often end up looking at shared ownership schemes, and the Housing Minister now calls property affordability a particular issue for the capital. The option to acquire Shared Equity Homes London buyer programs offer helps aspiring homeowners who cannot buy on the open market by letting them buy an initial share and pay regulated rent on the rest. A lender recently published a white paper by economist Rob Thomas, which builds on policy recommendations taken directly to No. 10 to address these housing market challenges.
Financial Realities and Challenges of Shared Equity Homes London
It uses data from MHCLG, the ONS, UK Finance, the Land Registry, and the FCA, plus a survey of 1,000 English households, to test whether today’s eligibility limits, income caps, and qualification rules still match real-world financial circumstances. Meanwhile, the upper chamber voiced sharp criticism regarding the risks associated with Shared Equity Homes London residents face: peers described the horror of unsellable and unmortgageable properties, called the situation Kafkaesque, and accused social landlords of predatory behaviour, pecuniary advantage, and conflicts of interest. These affordability pressures now hit shared ownership buyers and households of every kind, and every property owner in the scheme feels them.
1. Eligibility and Income Caps
Buyers qualify only with a gross household income of no more than £90,000 in the capital, or £80,000 outside London, and the government counts the result as affordable housing. Those stringent restrictions have stayed put since 2016, even though house prices rose 37% and earnings rose 42% up to 2025. Pepper Money took its findings to Downing Street, and Rob Barnard, its intermediary relationship director, says the housing market has moved on while the household income caps and income caps have not. One in ten non-homeowners above the limit tried the scheme and heard they were ineligible, and two thirds would join this tenure if the caps rose.
Couples in essential professions, such as teachers, nurses and paramedics, can cross the line on a median salary, yet they still lack the deposit or borrowing capacity to own a home on the open market. Zoë Garbett, Chair of the London Assembly Housing Committee, notes that buyers at the lower end of the wide income range feel the impact of rising costs most. In my view, the appetite is clearly there, so the sector and finance providers should check each buyer’s circumstances and let more people onto the housing ladder through shared ownership, as the white paper suggests.
2. Staircasing
Staircasing lets shared owners buy additional shares, grow their equity and cut their monthly rent, but Mr Pennycook, the housing minister, admits the process is complex and costly. He names resale fees, service charges and higher mortgage costs as the main affordability pressures, and interest rates make each step harder. The Regulator for Social Housing found that fewer than 2,000 London households reached 100 per cent in 2023, and a report says the pace in England sits at the lowest level in a decade. Baroness Hornhill links the barriers to rising property values, external wall standards and weak buyback options, while the G15 Residents’ Group wants a pilot that cuts rates so people own homes outright.
Will Jeffwitz, head of policy at the NHF, still calls the model one of the secure routes to homeownership, and the government is reforming the shared ownership model with smaller staircasing increments and more flexibility to improve customer experience and outcomes. A review will test ongoing affordability, the challenges owners face, and whether the route to full ownership works, because full ownership and 100% ownership remain the goal in London.
3. Service Charges and Ongoing Affordability
Londoners feel service charges the most, because the capital has the highest proportion of leasehold homes, so leaseholders often pay ground rent and unregulated service charges. Zoë Garbett and the London Assembly Housing Committee ran an investigation, and assembly members warn that high interest rate mortgage payments and large increases wear down affordability. They told the mayor to add designing down service charges to the London Plan.
A recent ruling in Battersea saw a landlord lose its appeal after it tried to pass the cost of amenities for private owners on a large estate to shared owners. That case shows why transparency and clear cost apportionment between landlord and tenant matter, from repairs obligations to other housing costs. Lord Young says the government holds no national data on equity loss or ongoing affordability, and he points to homes that turn unmortgageable once leases too short appear.
Lord Fuller adds that financially unsophisticated buyers need proactive information and better information at the time of sale, and he wants legislative changes or regulatory changes to protect their path to full ownership.
4. Government Response, Reform and Policy Review
The Budget will confirm the household income cap and local property price caps for the Your First Home scheme, which offers first-time buyers a government-backed equity loan of 20% on a new-build home with a minimum deposit of 2.5%. Rob Barnard argues that sensible eligibility rules should link building more homes, suitable properties and mortgages so people can climb the housing ladder. In the House of Lords, Lord Young of Cookham won an amendment to the Social Housing Bill, and a clear majority backed it.
Peers then held a debate in which Lord Fuller accused ministers of victim-blaming, pointed to unfair terms, an asymmetry of risk and reward and the pricing power of RSLs, short for registered social landlords. Lord Young asks whether sales during the nomination period prove the current model is financially sustainable. Matthew Pennycook, the MP for Greenwich and Woolwich, told the Commons Housing, Communities and Local Government Committee on 10 February that he sees specific problems and regional discrepancies in consumer experience. Shared Ownership Resources welcomed the vote, the Shared Owners’ Network called it a wake-up call, and Will Jeffwitz of the NHF backs consistency in buyback policies and further reform. Another review of financial realities will help Londoners most.
Dual-Income Limits and Financial Barriers for Shared Equity Homes London
The Dual-income gap shows how two full-time employees in the same job can beat the limit. Pepper Money studied key-worker occupational groups that employ 2.9 million people, and in seven of the ten the pair earned too much on a median salary. Two teaching professionals bring in about £95,000, nursing practitioners about £92,100 and paramedics about £107,600, yet one in five still could not buy because of deposit requirements, local house prices and childcare costs.
Among those surveyed, 58% live in privately rented accommodation and spend a third of monthly take-home income on rent. Older buyers matter too, since buyers 50 or over made up 18% of purchases in 2024–25, against 5% in 2003–04. Of those aged 45–54, 74% feel they are running out of time, and 46% of those aged 55–64 worry that a short mortgage term will hurt them. As Rob Barnard says, aspiration does not stop at fifty, and the same goes for essential roles in every town.
Buyback Challenges and the Future of Shared Equity Homes London
Buyback is the next big issue, because an equity repurchase stays discretionary for each registered provider. Homes England guidance tells providers to post their buyback policy on their website, and the Shared Ownership Code also asks for support during financial hardship. Even so, Homes England funded only 41 requests in the last three years, a tiny share of the post-Grenfell scandal cases where building safety problems leave owners unable to sell or remortgage a critical challenge for those invested in Shared Equity Homes London initiatives. Lord Young wants a dedicated allocation within the Social and Affordable Homes Programme, or SAHP, run by transparent national criteria, and he raised the idea during the Renters’ Rights Act.
Government Policy Solutions for Shared Equity Homes London
Baroness Watkins suggests a government grant mechanism that turns bought-back homes into social rented units, which would cut temporary housing and bed and breakfast use. Baroness Hornhill and Shared Ownership Resources back the idea, and the NHF urges housing associations to sign the Shared Ownership Code. Long lease terms matter here too. Sir Sadiq admits the scheme will not suit everyone, and City Hall now puts social rent first after starting 42,070 homes in the 2016-2023 Affordable Home Programme, also called the AHP. Overall, Shared Equity Homes London properties account for about 60,000 such units, while the other UK regions hold 190,000.
FAQs
1. Who is eligible to buy shared equity homes london?
To qualify for shared equity homes london, your annual household income must generally be £90,000 or less. You must also be a first-time buyer or a previous homeowner who cannot currently afford to buy a home outright on the open market.
2. How much deposit do I need to get started?
You typically need a deposit starting at just 5% to 10% of the share you are purchasing, rather than the total market value of the home.
3. Can I buy a larger share in my home later?
Yes, through a process known as staircasing. You can buy additional portions of equity in your home over time as your financial situation improves, up to 100% full ownership in most cases.
4. Do I have to pay rent on the unowned share?
In shared ownership models, you pay a reduced rent on the share owned by the housing provider. In pure shared equity schemes, you own 100% of the property with an equity loan covering a portion, meaning there is usually no ongoing rent.
5. What are the key advantages of buying shared equity homes london?
The main benefits of shared equity homes london include significantly lower upfront deposit requirements, reduced initial mortgage costs, and a more accessible path to getting on the London property ladder.