Commercial property investment is one of the smartest ways to build long-term wealth in the UK, and after years of working alongside investors, landlords, and lenders, I have seen firsthand how the right approach turns a simple purchase into a lasting asset.
The UK stands as the second-largest and one of the most lucrative property markets in Europe, with a total value that crosses £680 billion. This includes everything from shops and hotels to restaurants, pubs, bars, retail units, industrial warehouses, and factories.
Our three-part guide walks new investors, seasoned buyers, and first-time landlords through the full journey of investment transactions, acquisitions, and financing, so that every decision you make is backed by real understanding, not guesswork.
What Is A Commercial Property Investment Transaction?
At its core, this kind of transaction means buying, selling, or transferring ownership of a building that already has tenants inside it. Some deals are simple, involving a single site with one tenant.
Others grow into complex, multi-let investments with several tenants and multiple income streams running side by side. Every deal carries its own legal, financial, and operational considerations, so a structured approach is not optional, it is essential for protecting your investment.
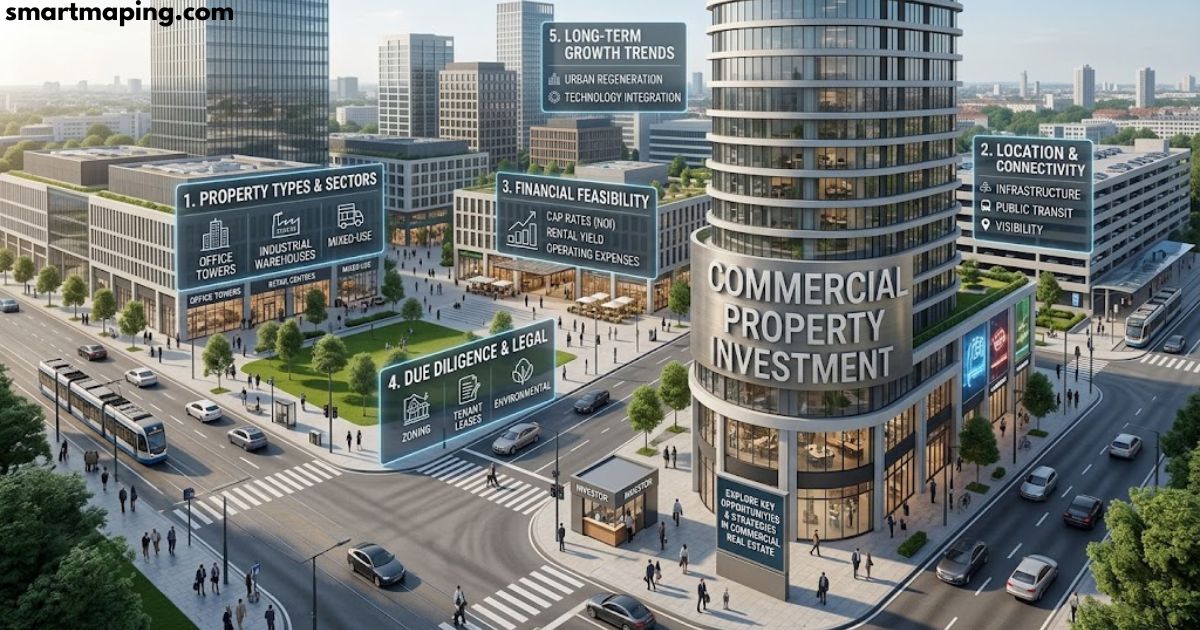
Whether you are a business investor, a landlord managing a growing portfolio, a pension scheme protecting its members, or a lender securing your position, the appeal is the same: stable income, steady growth, and long-term security.
Commercial assets typically deliver prime yields of 5–8%, which often outpaces residential buy-to-let. This is exactly why so many people now see commercial property investment as a smarter, more rewarding path than sticking only to residential options.
The Importance Of Proper Due Diligence
Rushing into a purchase without proper due diligence is one of the costliest mistakes an investor can make. Skipping this step can expose you to hidden title defects, unresolved restrictions, or breaches of planning and environmental law that surface only after you already own the property.
A thorough review also uncovers tenant issues such as unpaid rent, disputes, or poorly drafted leases, all of which can hurt the value of your asset and make it harder to resell or refinance later. Good due diligence protects your future, not just your purchase.
What Are The Key Steps When Considering An Acquisition?
Every solid acquisition follows a clear, structured path. It begins with heads of terms, which outline the basic agreement before legal drafting starts. From there, lawyers investigate the title, lease details, planning status, and compliance records, and compile everything into a report you can actually use.
Once the legal documents are drafted and negotiated, including the contract, transfer, and any supporting paperwork, the deal moves to exchange and completion. Exchange locks in your commitment, and completion transfers ownership and funds. After that comes post-completion work: filing Stamp Duty Land Tax returns, registering any legal charge, updating the title at HM Land Registry, and notifying tenants of the change in ownership.
What Are The Common Legal Structures In Investment Transactions?
Many buyers choose specific legal structures purely for tax efficiency and risk management. Special Purpose Vehicles, or SPVs, are companies created solely to hold a property, which helps limit personal liability.
Pension schemes are another popular route, often providing a more tax-efficient income stream. Trusts, meanwhile, suit those focused on estate planning or more complicated ownership arrangements. The right structure always depends on your personal goals, tax position, and financing needs.
Route 1: Direct Buy-to-Let
Buying a property outright, or financing it through a commercial mortgage, and then leasing it to a tenant remains the most traditional route into commercial property investment.
Commercial mortgages usually carry higher interest rates than residential loans, and investors typically need a deposit of 20–40% of the property’s value. Long-term leases, however, often reward this effort with stable income and fewer empty periods.
Route 2: Long-Term ‘Fix-and-Flip’
This approach involves buying a building, often using a bridging loan, then upgrading or redeveloping it to raise both its value and rental potential. Once improved, the property can command higher rents, attract stronger tenants, and sell for a better price. It suits investors who prefer creating value through improvement rather than waiting on the market alone to deliver growth.
Route 3: Short-Term Flip
Unlike the fix-and-flip, this route skips major renovation work entirely. It relies on buying at a competitive price, quickly finding a motivated buyer, and selling for a profit within a short holding period. It can deliver fast returns, but only for those with strong market knowledge and confidence in buyer demand.
Route 4: Indirect Investment
Not everyone wants the responsibilities that come with owning a building outright. Indirect investment, through REITs, collective investment schemes, or shares in property companies, offers a hands-off way to gain exposure to the market. It brings flexibility and portfolio diversification without daily management concerns.
Right time to Invest In Commercial Property?
Timing matters. Before buying, check the overall value of properties in your target area, along with supply, availability, and the general condition of what is on the market. This groundwork helps you avoid overpaying and keeps your future commercial property investment on solid footing.
Availability of commercial mortgages
Lenders vary widely in how flexible they are. Some offer generous terms across many property types, while others stay far more cautious. Researching this properly, across the whole UK before narrowing to your target area, saves real frustration later.
Looking to become a landlord?
Becoming a commercial landlord means understanding local rental demand, checking comparable listings, and pricing your property sensibly. A high-quality building with strong facilities can attract reliable, financially secure tenants, even if it carries a slightly higher upfront cost.
Finding a property that’s the perfect fit
Buying a commercial building brings costs well beyond the deposit. Stamp Duty applies above £150,000, alongside VAT in some cases, legal and consultancy fees, and ongoing costs like insurance, business rates, maintenance, and energy bills. Every serious commercial property investment plan should budget for these from day one.
How to invest in commercial property with financing
A commercial mortgage remains the simplest way to fund a purchase. Today’s lending market includes far more than high street banks, so get your business plan, bank statements, and accounting records ready before applying, and consider working with a specialist advisor.
Location
Location shapes performance more in commercial property than almost anything else. Retail businesses often want high footfall and strong transport links, while other sectors care more about supplier access or proximity to clients. Good access, whether by road, rail, or air, always adds long-term value.
Freehold vs leasehold commercial properties
Leasehold makes up most commercial stock, but freehold ownership offers permanence, potential appreciation, and the freedom to expand or sub-let. It comes with a higher price tag and larger deposit, so weigh the trade-offs carefully before committing.
FAQs
Is it worth investing in commercial property?
Yes, for most patient investors, commercial property investment rewards you with stable income and long-term capital growth, often outperforming residential options through stronger prime yields. It takes real commitment, but the payoff genuinely feels worth the wait.
Is 20k enough to invest in property?
On its own, £20k rarely covers a full deposit for direct ownership, but it can work well as a starting point for indirect investment through REITs or collective investment schemes. It is a realistic, low-pressure way to enter the commercial property market.
Are commercial property prices falling?
Commercial property prices have shifted unevenly across the UK, with some sectors softening under higher commercial mortgage rates while others, especially industrial and logistics space, hold steady value. It really depends on location and property type.
What is the biggest problem in commercial real estate?
The biggest challenge remains rising borrowing costs combined with cautious lenders, which slows financing and puts pressure on rental income and property values. Many investors find this uncertainty the hardest part to plan around.
What is the average return on commercial property in the UK?
Commercial property in the UK typically delivers average returns between 5–8% through rental yields, alongside potential capital growth over time. It remains one of the more reliable paths to steady, long-term income.