Buying a house, a condominium, or an apartment complex counts as one of life’s biggest milestones, and it usually demands a substantial, significant financial commitment. Anyone who has recently purchased into property ownership, or who has been owning rental properties for years, needs a clear guide and robust Property Owners Insurance to protect that long-term investment.
This blog post shares practical insights so you can discuss your property’s insurance needs with confidence, understand the unique risks each building carries, and know why transparency about necessary information gives you peace of mind when you ever need to file a claim. Getting properly equipped with the right cover is a top priority and a crucial step in safeguarding and protecting your residential property owners insurance assets for the future, and true understanding of your policy is what makes securing that safeguard worthwhile.
What is Residential Property Owners Insurance?
Residential property owners insurance, often called landlord insurance, is a specialised insurance policy built for individuals and entities who own residential properties. This type of insurance wraps a wide set of coverage options around your building, ensuring you stay shielded from the various risks and liabilities that come with renting out a home. Because every landlord’s situation looks different, insurers design these policies with property owners in mind, commonly known for their flexibility and their comprehensive, associated protection.
Protecting Your Property
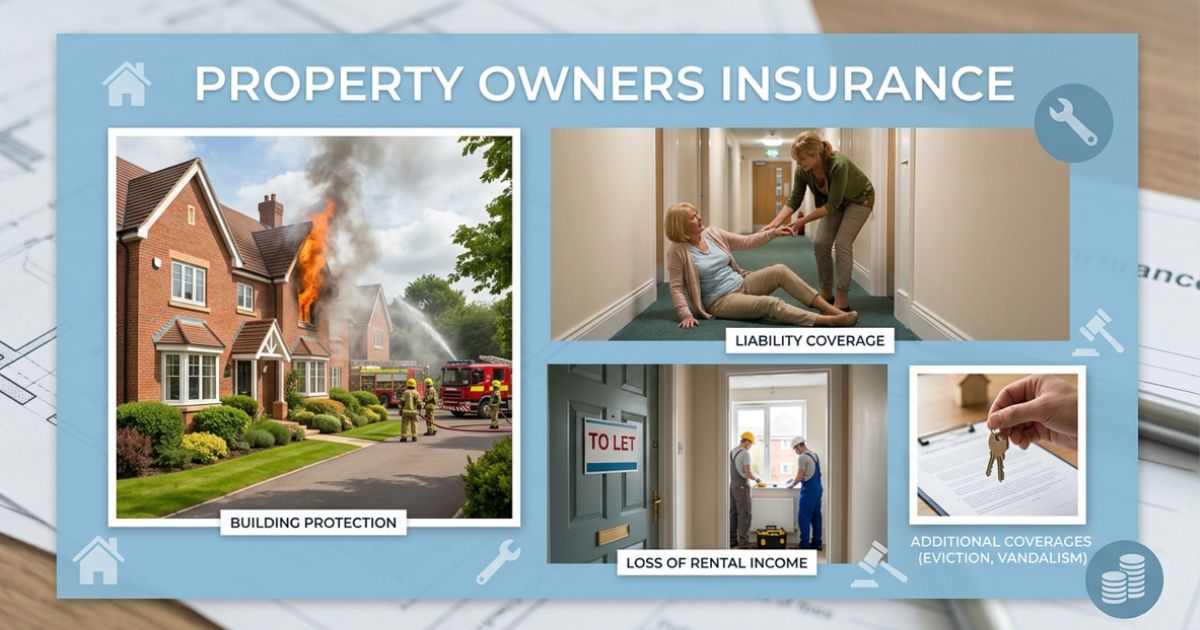
The core job of residential property owners insurance is to protect the physical structure of your building, and this is one of its primary functions. It covers damage caused by fire, vandalism, severe weather events, and other perils, and when an unfortunate event like a natural disaster strikes, repairing or rebuilding a property can prove exorbitant. With insurance in place, you can rest assured that these expenses will be handled, reducing the financial burden and the true cost you would otherwise carry alone.
Liability Coverage
Accidents happen, and property owners can be held liable for injuries sustained by tenants or visitors on their land. Residential insurance typically bundles in liability coverage, and this section helps protect you by covering medical expenses, legal fees, and settlements if someone sues you over an injury on site. In today’s litigious society, this kind of cover is essential, because it keeps your personal assets out of risk.
Loss of Rental Income
When a property becomes uninhabitable after a fire or a severe storm, you can lose rental income while repairs get finished. Residential property owners insurance often adds cover for exactly this loss of rental income, which protects your cash flow through challenging times. This part of the policy exists to keep money coming in even when the building itself cannot be lived in, since insurers know landlords still have bills to maintain, and it covers income lost to covered perils specifically.
Additional Coverages
Depending on your situation, residential property owners insurance can stretch to additional coverages built around your specific needs. Landlord liability insurance can pay legal expenses if you ever need to evict a tenant or take legal action against them, while vandalism coverage protects your property from acts of vandalism. These extras let you protect exactly the parts of your investment that matter most to you.
Peace of Mind
A comprehensive insurance policy brings real peace of mind, and this benefit sits among the significant benefits of holding proper insurance. Knowing your cover is solid helps alleviate the stress and anxiety that come with property ownership, so you can focus on the growth and management of your real estate portfolio instead of worrying about unexpected events. This freedom from financial consequences is what lets landlords sleep easier at night.
What’s inside the guide?
A good policy always excludes certain situations, so it pays to know them before a claim ever comes up. If you were aware of a defect that caused an incident and you did not take reasonable steps to fix it, the insurer may decline the claim over negligence or failure to maintain the property. Deliberate acts and intentional damage or injury sit outside every set of liability policies, and separately, any liability arising from motor vehicles falls under motor insurance rather than property owners liability, even though the vehicle itself may be covered under its own policy and the known defects clause still applies.
Who Needs Property Owners Liability Insurance?
Anyone who owns property and lets third parties onto it whether as tenants, visitors, or members of the public should carry property owners liability insurance. Residential landlords letting single properties, buy-to-let portfolios, HMOs, or blocks of flats fall into this group, since tenants have a right to a reasonable standard, and even minor maintenance oversights can lead to a liability claim. Commercial property owners letting offices, retail units, industrial premises, or mixed-use buildings face similar exposure, because commercial tenants and their customers may find grounds to claim if the property’s condition causes damage or injury.
Property developers who own buildings during construction or renovation still carry liability risk, since unoccupied properties can still affect trespassers, contractors, and neighbouring properties, and property portfolio investors managing multiple properties across different locations know that one single liability claim on a large portfolio can prove significant, which is why consistent liability cover matters everywhere their buildings sit, whether tenants are maintained on site or the space is left access-restricted.
How Much Cover Do You Need?
Most property owners liability policies offer indemnity limits of £1 million, £2 million, or £5 million, and the appropriate level always depends on the type and scale of your property interests. Residential landlords with one or two properties usually find £2 million typically sufficient, while larger portfolios, commercial properties, or buildings with high footfall may need £5 million or more, and some lenders and managing agents set a minimum level as a condition of a mortgage or management agreement. Liability claims involving serious personal injury can result in large compensation awards, so underinsuring on liability cover remains a significant risk worth avoiding.
Is It Included in a Property Owners Policy?
Yes in the UK, property owners liability cover almost always sits inside the standard section of a property owners insurance policy, alongside buildings cover and optional extensions such as loss of rent, contents, and legal expenses. It is not usually sold as a standalone product, so when arranging cover, you should always confirm that the liability section is included and check the indemnity limit carefully.
Why Every Landlord and Commercial Investor Needs Property Owners Insurance
Picture a tenant in a block of flats who slips on a wet communal staircase and suffers a broken wrist; when the claim argues the landlord failed to maintain proper non-slip surfaces, the Property Owners Insurance liability section covers the legal costs and compensation. Elsewhere, a loose coping stone falling from the parapet of a commercial building might damage a parked car, giving the vehicle owner grounds to claim against the property owner, or a burst pipe in a first-floor flat could flood the ground-floor unit below, damaging a ground-floor tenant’s furniture and personal belongings, and again the Property Owners Insurance policy responds.
A visitor who gets injured when a defective gate swings back and strikes them can also bring a resulting personal injury claim, and this kind of escape of water, falling masonry, or slip and fall is exactly why every commercial property owner keeps Property Owners Insurance close at hand.
FAQs
What is property owners insurance and what does it cover?
It protects building owners against risks like fire, storm damage, theft, and third-party liability, covering the structure and liability with optional loss of rent coverage.
How does landlord insurance differ from standard home insurance?
Standard home insurance only covers owner-occupied homes, while landlord insurance covers properties rented to tenants or used for business, including public liability and tenant risks.
Is building insurance legally required for rental properties?
It isn’t legally mandatory, but mortgage lenders almost always require active insurance as a loan condition to protect against structural loss.
What factors influence property insurance premium costs?
Premiums depend on property location, building age, occupancy type, past claims history, and the total estimated rebuild cost.
How much property owners insurance do I actually need for my building?
Coverage should equal the full estimated rebuild cost including professional fees and site clearance rather than the property’s current market value.